


The Toaster Era Returns
The bank realizes it needs to compete in the future of finance, and it’s one where agents roam freely in low-friction environments.
In 1933, America was deep in the Great Depression.
In response to the crisis, Congress passed the Banking Act of 1933. The law, also known as Glass-Steagall after its sponsors, Carter Glass and Henry Steagall, shook up American banking.
It forced Wall Street to choose between commercial and investment banking. It created the FDIC and federal deposit insurance, and gave the Fed more oversight of bank lending practices.
It also did something else few people know about. It implemented Regulation Q, which let the Fed cap the rates banks could pay on savings accounts.
The thinking was that banks had been competing for deposits by raising deposit rates and writing riskier loans to cover the costs. Capping deposit rates would make bank failures less likely.
For decades, the rule didn’t matter much. It helped banks secure cheap funding and discouraged them from writing risky loans to chase higher profits.
But in the 1960s, market interest rates began creeping well above the Regulation Q cap.
Inflation was running hot. Before long, Treasurys and bonds were offering more than double what a bank was allowed to pay. Keeping money in a checking or savings account meant losing purchasing power every year.
The banks couldn’t entice depositors with higher rates. The law made sure of that. But they had to offer customers something.
Enter the toaster…
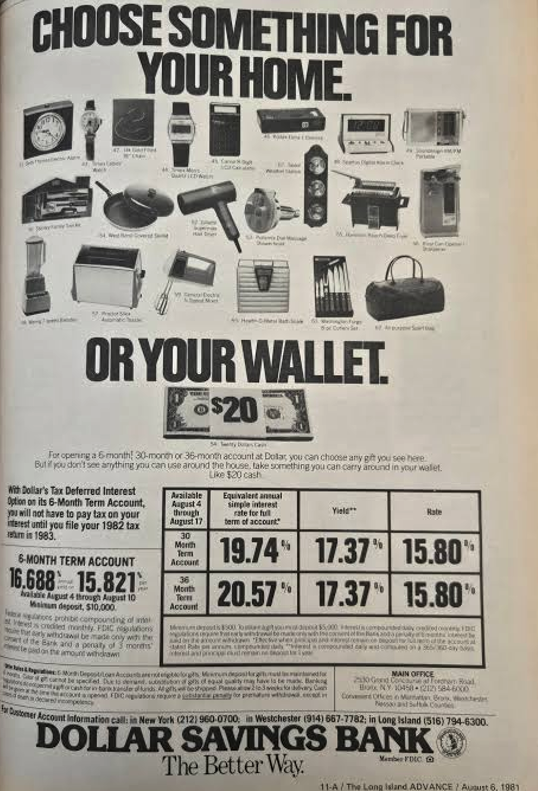
In the 1960s and ’70s, it was common to receive a home appliance as a reward for opening a new checking account.
That alone wouldn’t have been enough to keep deposits from flowing into higher-yielding Treasurys. But in 1970, the Treasury raised the minimum purchase size of Treasury bills from $1,000 to $10,000 (about $89,000 inflation-adjusted), pricing ordinary savers out of buying them directly.
But it didn’t matter.
Money market funds innovated to fill the gap.
They offered competitive rates by solving the $10,000 problem. Individuals pooled their money inside the fund, and the fund bought the Treasurys on their behalf.
This let everyone get the exposure they craved.
The funds didn’t stop there. They lowered withdrawal limits, added check-writing, even offered cards to access the money.
It was a moment when friction kept falling and, for once, the financial industry was making concessions to earn a customer’s business.
It got to the point that banks lobbied Congress hard to regulate away the funds’ advantage. It was clear banks couldn’t compete. And rather than innovate their way out of the mess, they asked the government to protect them.
If that sounds familiar, it should. They’re doing it today.
Recommended Links
Live… From Inside Cybercab
I’m about to get into this Cybercab… and it’s going to take me to what Elon Musk called… “The most epic AI project ever.” Click here and come with me on this ride… Because this is all part of Elon Musk’s $320 trillion masterplan.
Trump Goes "All-In" on Grand Canyon Energy Breakthrough
On July 4th, Washington killed the tax credits for solar, wind and EVs. One energy source got the opposite. Eight years of credits. Right alongside oil and nuclear. It's the well a crew hit near the Grand Canyon. Almost 8X the output of Saudi Arabia's biggest oil well. Google's in. Gates is in. On October 20th, the feds auction 83 new parcels for it. One company owns the entire chain. Get in before the gavel drops. Get the Grand Canyon breakthrough ticker here >>
Banks Already Gave Away Your Password
Citigroup and Bank of America are the latest U.S. banks to restrict AI agents’ access to customer accounts. If you want an AI agent to automate some of your banking, you’re out of luck.
The two join a growing list that includes JPMorgan Chase, Charles Schwab, and Wells Fargo. This new anxiety has a name – Muse, courtesy of Meta (META). It’s an easy-to-use AI assistant that can act on a user’s behalf. Simply tell it what you want it to do… and it does it.
At the top of the list: shopping. That means access to users’ bank accounts. That’s when the door slammed shut.
Each bank cites its own reason.
JPMorgan’s Jamie Dimon framed it as risk and liability on the bank’s third-quarter earnings call. The bank said it won’t let just any outside agent in because it’s too risky for customers and the bank alike.
Bank of America’s Brian Moynihan struck a similar tone, arguing a human needs to stay in the loop. Others point to the danger of handing an agent your password.
That last one is rich.
Banks are worried your agent might leak your password… the very password the banks themselves already gave away.
JPMorgan Chase’s 2014 data breach affected 76 million households and 7 million small businesses. Capital One’s 2019 breach compromised roughly 100 million people in the U.S.
Between them, the exposed data included names, addresses, phone numbers, and emails. In Capital One’s case, about 140,000 Social Security numbers and 80,000 bank account numbers were also exposed.
It wouldn’t be surprising to learn that a meaningful share of credit fraud traces back to hacks like these.
Then there’s First American Financial, which exposed 885 million documents spanning 2003 to 2019. They included bank statements, Social Security numbers, and mortgage records.
But, sure, letting an agent buy paper towels for you is the real security risk…
The worst part is that the First American breach required no hacking skills at all. The documents sat on a public-facing website, readable by anyone who changed a number in the link. It was simply the result of human stupidity, indifference, or both.
So, no.
Somehow, I doubt that protecting the sanctity of their users’ personal information is the real motivator for shutting down agentic finance.
So, what is?
The $47 Billion Secret
JPMorgan Chase, Bank of America, and Wells Fargo collectively hold $1.6 trillion in noninterest-bearing deposits. That’s about 16% of their liabilities.
It’s money they pay nothing on and lend out at full market rates.
If they had to pay a measly 3% on those deposits, roughly $47 billion a year would flow to you and me instead of them. That’s about 40% of their combined net income over the past year.
The real fear about letting agents into your accounts is that AI can do simple math.
We covered this in “The Agentic Bank Run.” An agent instructed to maximize the yield on your idle cash will not leave money at a major bank earning 0.1% when 4% is one transaction away. And while shuttling your money into a higher-yielding account may be arduous for a human, it’s child’s play for an agent.
Billions will flow out of low-yielding bank accounts and into higher-yielding, highly liquid money markets.
And there goes the banks’ margins…
Barring AI agents from accounts is a last-ditch effort to slow the outflow. Banks are already winning over regulators and lobbying Congress on this exact concern.
But here’s where things get a bit more interesting… One bank is trying to get ahead of it.
The Stablecoin Moat
JPMorgan just announced that its tokenized deposit, JPM Coin (JPMD), is live on Ethereum.
Understand what that represents. A Wall Street bank has now put some of its infrastructure on a public and permissionless blockchain.
This is the same bank that spent years touting Kinexys, its permissioned blockchain unit (formerly Onyx), as the institutional alternative to public networks.
And while JPMD itself launched last November on Base, it’s now on Ethereum mainnet.
The bank chose Ethereum for the depth of its onchain liquidity and tokenized assets.
The walled garden is becoming a distant sales pitch. The bank realizes it needs to compete in the future of finance, and it’s one where agents roam freely in low-friction environments.
There is an important difference between JPM Coin and regular stablecoins. It comes down to what banks fought so hard to protect. They lobbied to ensure stablecoins such as USDC and USDT cannot pay yield to holders.
Tokenized deposits such as JPM Coin can. That’s the regulatory moat they built.
But it likely won’t work.
The moat comes with friction. JPMD is available only to vetted institutional clients, and every compliance layer the bank adds is a reason for users to route around it.
Meanwhile, Aave already pays around 4% on USDC deposits, with a promotional rate near 7% for users of its new mobile app. Robinhood is running its own introductory offer with a similar rate, and Coinbase is throwing its hat in the ring too.
JPMorgan’s tokenized deposit will need to do more than exist on Ethereum. It will need to interact with the rest of DeFi. We’re talking lending pools, vaults, the venues where yield exists.
Will JPMorgan do it? I’m leaning no.
I think the bank will first try to roll out a JPM Coin-specific DeFi app on Ethereum before coming to terms with reality.
But instead of wondering what it’ll do, let’s step back and look at where we are right now.
Banks fear AI agents accessing checking accounts. They know it will lead to mass deposit flight. That, in turn, will imperil their profits.
To prevent that, banks can either:
- Dive into the DeFi arena headfirst and compete for deposits with higher yields
- Ward off the inevitable by building themselves a regulatory moat
They’re choosing No. 2… for now.
Have they tried bringing back the toaster?
Your Pulse on Crypto,
Ben Lilly
Editor, Chain of Thought
Continue following Brownstone Research
Add Brownstone Research as your preferred source on Google to see our latest stories in your feed.
 Add as a preferred source
More stories like this
Read the latest insights from the world of high technology.
-
-
-
Suddenly, the Pond is Covered
It’s a good way to visualize how big, consequential changes can sneak up on you.