

The Toaster Era Returns
The bank realizes it needs to compete in the future of finance, and it’s one where agents roam freely...

JPMorgan can keep both pieces of infrastructure as long as it likes. But customers will decide where to do business.
Editor’s Note: According to Jeff Brown, the AI industry is on the verge of a transformation, and one California-based company is at the center of the story.
On October 28, Jeff is going live with all the details, including why previous winners in the AI space could fall hard and why a new crop of AI stocks could climb higher. Get all the details for yourself right here.
Blockbuster had thrown everything at Netflix “but the kitchen sink.”
That’s what Reed Hastings, co-founder and former CEO of Netflix, said on a conference call in January 2005.
By then, the largest video rental chain in America had cut prices, launched its own DVD-by-mail service, and spent heavily to bury the upstart.
Despite the onslaught, Netflix was still standing.
The next day, a large box from a home improvement store arrived at Netflix headquarters.
Inside was a kitchen sink. The sender: Blockbuster.
You know what happened next…
Blockbuster filed for Chapter 11 a few years later. Netflix became…well…Netflix.
But here’s the part most don’t know…
In the early 2000s, Blockbuster tried to beat Netflix in the DVD-by-mail game, but Hastings was playing a different game altogether.
Between 2005 and 2007, he quietly funneled 1% to 2% of revenue into a streaming project. The goal was to kill DVD-by-mail.
But in public, Hastings said the opposite.
He told investors Netflix had at least a decade of DVD dominance ahead of it. Streaming was “coming,” but it was an afterthought in the story pitched to Wall Street. The discs were here to stay.
Of course, they weren’t…
By January 2007, American broadband was fast and widespread enough to support streaming. That month, Netflix launched a service called “Watch Now,” and the rest is history.
Streaming was out of the bag.
Years later, Hastings made the separation official. He moved the DVD operation into a different building, and its executives stopped attending Netflix management meetings.
The logic was simple. Anyone whose paycheck depended on the old business would find a way to protect it. The new thing had to be protected from the old thing.
Watch what I do, not what I say.
That was the Netflix playbook. And it’s exactly what’s happening on Wall Street now, with one important difference.
The man who called the bottom of the 2020 crash to the day and recommended seven stocks that all went on to double is now unveiling his newest prediction for the stock market. An “AI Superchip” 50 times faster than Nvidia's could soon create a new order in the market. See his write-up and how you could make 10 times your money if you position yourself by October 28.
By the end of this month, Elon Musk is about to shock the world again. He’s predicting this NEW opportunity will be 180 times bigger than the SpaceX IPO… And will unleash enough wealth to make every household in America $2.38 million.
Wall Street is notorious for saying one thing and doing another.
JPMorgan Chase has made it an art form.
Jamie Dimon called Bitcoin a “fraud” in 2017 and said he would fire any trader caught touching it.
By 2024, he was calling it a “pet rock” at Davos. His lieutenants echoed the line.
In May 2024, Umar Farooq, then head of the bank’s permissioned blockchain unit, told a Bank for International Settlements summit that public blockchains were “not fit for purpose for large transactions today.”
The comments made sense coming from JPMorgan.
The bank has been building permissioned blockchains, the kind it controls, for a decade. It joined the R3 consortium in 2015, where a group of banks tried to build shared private ledgers.
In 2016, it forked Ethereum’s code into a private version called Quorum. It helped found the Enterprise Ethereum Alliance in 2017 and left R3 that same year.
Quorum’s projects rolled into Onyx, which became Kinexys in November 2024. Different names, same idea: Take the technology, preserve the gatekeeper.
Which is why the bank’s latest move is so interesting.
JPMorgan now has three products running on the permissionless infrastructure its executives said was not fit for purpose.
In December 2025, its asset management arm launched a tokenized money market fund on Ethereum, seeded with $100 million of the bank’s own money.
In May 2026, it launched a second one, a Treasury and repo fund trading under the ticker JLTXX.
And on Monday, Kinexys put JPM Coin, a token representing actual JPMorgan dollar deposits, on Ethereum mainnet.
The reason: Ethereum’s “established depth of onchain liquidity.”
Then, the same day, we got even more news.
JPMorgan Asset Management published its annual Long-Term Capital Market Assumptions. It’s the document that sets return expectations for trillions of dollars in client portfolios.
For the first time, Bitcoin was included. More interestingly, it ranked first, with a 10% expected annual return over the next 10 to 15 years. It sat ahead of private equity, REITs, U.S. large-cap stocks, and gold.
A fraud in 2017. The highest-returning asset class in the house view by 2026.
For years, JPMorgan tried to compete on DVD-by-mail. It has finally woken up to the age of streaming.
But here’s JPMorgan’s problem…
Hastings was wise enough to cleave the old business from the new, superior one. JPMorgan is doing the opposite.
Its public-chain products are stapled to Kinexys, the private-chain division. The same people who built the permissioned garden are running the public expansion. There is no separate building, no excluded executives, no willingness to let the old thing die.
Expect the bank to spend the next several years trying to salvage its permissioned infrastructure. It will pull clients and eventually retail into a walled garden. Perhaps it will touch public infrastructure at the edges.
But it won’t work. Mostly because a competitor is running the Hastings playbook better.
Larry Fink does not mince words on tokenization anymore.
BlackRock’s CEO went from skeptic to evangelist in a few short years. His 2026 shareholder letter said tokenization today “may be roughly where the internet was in 1996.”
And now, the rest of BlackRock is saying the same thing.
On Monday, Dan Maley, who runs BlackRock’s cash management business in Asia Pacific, told Bloomberg where the firm thinks tokenization goes next.
But first, some background…
When I talk about tokenization, I’m usually talking about dollars and assets flowing onto public blockchains and staying there to interact with protocols.
We rarely discuss the flow in the other direction: tokens moving back into the traditional financial system to stand in for the cash and securities that sit in brokerage and clearing accounts today.
That’s the flow BlackRock is describing.
Its tokenized money market fund, BUIDL, is already accepted as collateral by Binance, Deribit, and Crypto.com. A trader can post BUIDL shares instead of cash, keep earning Treasury yield on them, and trade against the balance.
Now, BlackRock wants BUIDL, and every other tokenized fund, to be pledged as margin at the clearinghouses and prime brokers that run Wall Street today.
The firm is pitching it as an efficiency gain. Investors could move fund holdings without redeeming to cash first. Collateral could settle at any hour instead of waiting for a transfer agent.
It’s a Trojan horse.
Because to accept a token as collateral, a clearinghouse must be able to hold one.
That means wallets. Custody of private keys. Running or paying for node services. Onramps and offramps between tokens and bank balances. Legal frameworks for what happens when a token moves at 3 a.m. on a Sunday.
It’s everything a firm would need to build on a public blockchain itself.
Once these traditional firms have it, the hardest part of going onchain is done.
This is the DVD-by-mail phase of the fight.
BlackRock is inviting Wall Street’s incumbents to upgrade their plumbing so they can compete with tokens on their own turf. They will do it because the alternative is losing collateral business to the exchanges that already take BUIDL. And every upgrade they make lowers the friction for the next dollar to go onchain and stay there.
Capital goes where friction is lowest. That has always been true, and tokens on public rails are the lowest-friction form of capital ever built. Once the traditional firms can hold them, the walled garden breaks down.
JPMorgan can keep both pieces of infrastructure as long as it likes. But customers will decide where to do business.
Nobody wants to build on a corporate chain.
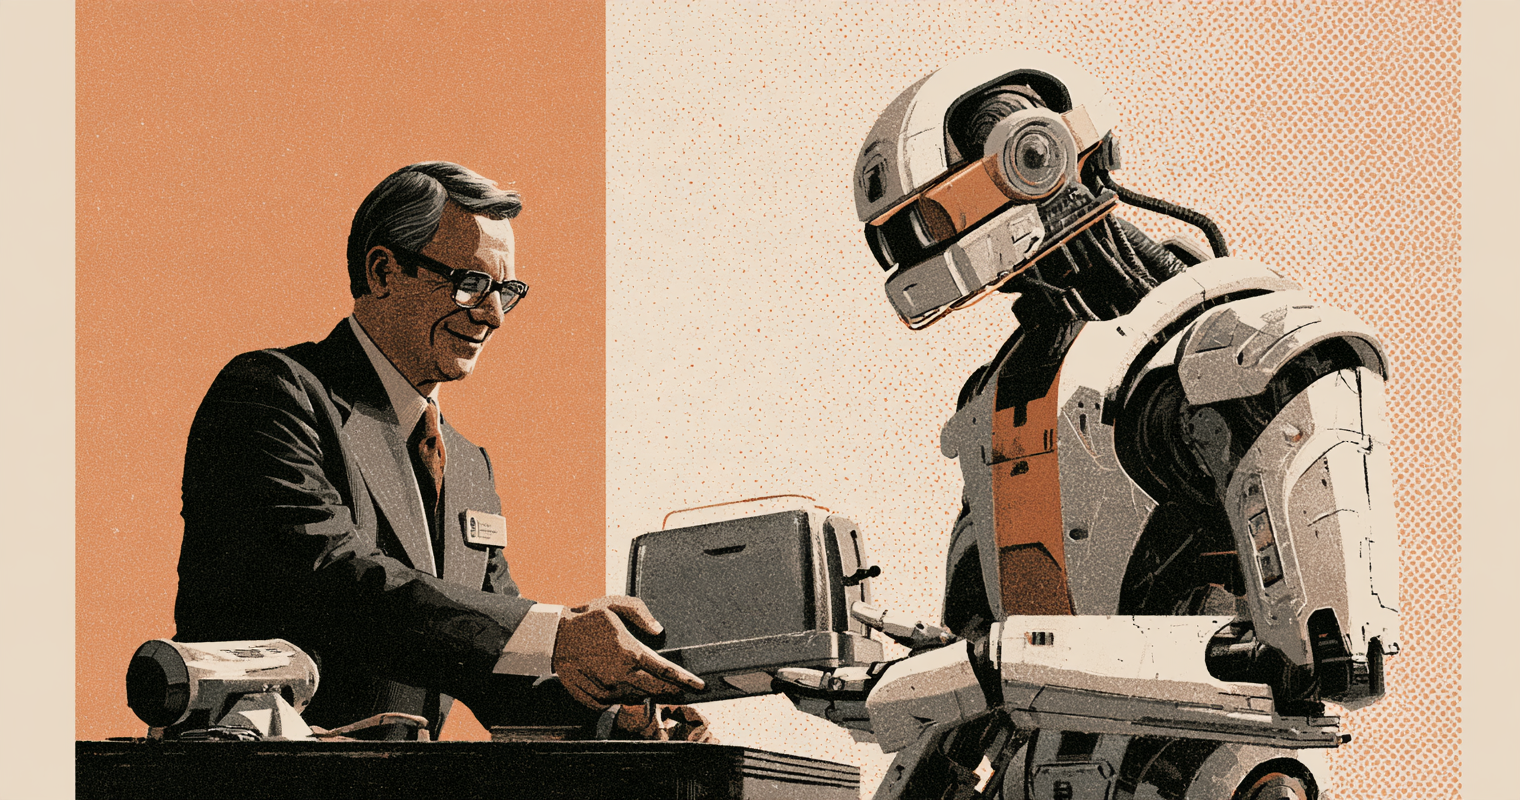
Pretty soon, Jamie Dimon will be sending the kitchen sink. And he’ll send it on a public chain.
Your Pulse on Crypto,
Ben Lilly
Editor, Chain of Thought
Add Brownstone Research as your preferred source on Google to see our latest stories in your feed.
 Add as a preferred source
Read the latest insights from the world of high technology.
The bank realizes it needs to compete in the future of finance, and it’s one where agents roam freely...